Sunday Summary: Tsunami Time for Real Estate?
By The Editors November 8, 2026 9:00 am
reprints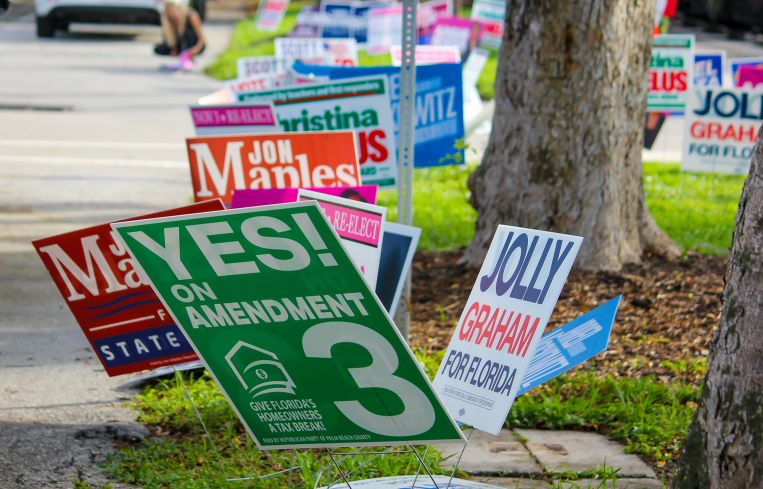
If last week was the time you finally booked that trip to Micronesia and decided to truly unplug — no phone, no TV, no newspapers, no laptops, no salt stomping Instagram videos — we have news for you:
There was an election. And you could have saved yourself a trip because the wave was bigger than anything you saw on the beach.
We’re speaking, of course, about the Blue Tsunami on Tuesday. Democrats will soon control both houses of Congress and will be governors in at least 27 states, including Texas, Ohio and Georgia.
Over at Commercial Observer the first question we asked was: What does it mean for real estate?
The two biggest areas this will affect are probably housing and data centers.
We’ve talked about data centers a lot recently (and their extreme unpopularity with the hoi polloi — although there might be ways to convince people that they’re not pure evil), but for the moment let’s examine the housing side of the ledger.
“Washington can’t solve New York’s housing shortage on its own, but it can make housing dramatically easier to finance, approve and build,” said James Whelan, president of the Real Estate Board of New York in the wake of the election. “Congress should reward production, expand the capital available for affordable housing, remove unnecessary federal barriers and ensure that the programs it has already authorized are actually funded.”
Texas Sen.-elect James Talarico sounded on board, saying he wanted to reduce red tape in homebuilding.
And, beyond simple encouragement and lifting stumbling blocks, California Rep. Maxine Waters — who will probably chair the House Financial Services Committee — has already called for $1 trillion in housing investment, aimed at reducing homelessness and aiding low-income homeowners.
Plus, New York Rep. Alexandria Ocasio-Cortez’s Homes Act — her $30 billion proposal which would acquire distressed housing and make it permanently affordable — might very well receive a second look from a Congress that has swung sharply to her party.
Of course, Tuesday’s election wasn’t just congressional. On a state level, we saw Florida voters approve Amendment 3, which would cut the current property tax increase cap in half — which, for a state with no income tax, might mean a big hit to Florida’s coffers and a lot of unforeseen consequences. Voters also rejected Robert Rivani’s proposal to build an office development in South Beach, and RCI Marine Group and Suntex Marinas’ plans in Virginia Key.
As of Friday, California’s Proposition 45 was too close to call — which is no doubt making developers nervous. This was the proposal that would curtail environmental rules to speed up the approvals process. But opponents are saying it’s a Trojan Horse for slipping data center development into California. (We told you data centers are unpopular.)
In last week’s Sunday Summary we noted a slew of earnings calls, and they kept on coming.
The largest publicly traded apartment REIT — the newly merged AvalonBay Communities and Equity Residential — kicked off its first earnings call as Vivmark Residential with news that it accrued $1.19 billion in revenue and its net operating income was $800.76 million. Vivmark also said their occupancy rate was an enviable 95.8 percent, they finished two new projects adding 761 new units to their portfolio, and they have a $4.4 billion multifamily pipeline. (But it wasn’t all peaches and cream — they also reported a $747 million loss for the quarter.)
There’s no putting much gloss on the fact that Starwood Property Trust had a pretty abysmal quarter, with a 95 percent annual net income drop and a net loss of $389.7 million.
Simon Property Group, on the other hand, surpassed expectations with $1.8 billion in revenue for the quarter (13.3 percent than last year) and occupancy reaching 96.5 percent.
Brookfield Asset Management isn’t having trouble getting investors to believe in it — they announced a $25 billion fundraising haul (so far they’ve raised $123 billion in 2026!) and saw revenue shoot up 72 percent to $2.1 billion.
Cushman & Wakefield saw a nice uptick in revenue ($2.8 billion) compared to the third quarter of last year ($2.6 billion), and net income was also up ($52.1 million versus $51.4 million).
“We’ve done the difficult work, lowered our interest costs and our leverage, earning recent rating upgrades from both Moody’s and S&P Global and generating stronger free cash flow,” noted C&W’s global CEO, Michelle MacKay. “Simply put, our balance sheet has been transformed. We enter this next period from a position of increasing stability and flexibility. Having executed our deleveraging plan, we expect to move to a more balanced capital allocation strategy.”
Mall giant Macerich could likewise boast a rise in net operating income and also a push to get its house in order under CEO Jackson Hsieh’s “Path Forward Plan.” (It was a slightly uneven performance — Macerich also reported a loss on the quarter, but considerably lower losses than last year, and a healthy 94.9 percent occupancy.)
Empire State Realty Trust signed 170,608 square feet of office leases over the quarter, raising its occupancy from 89.1 to 91.9 percent, and sold 1359 Broadway to Thor Equities for $217.5 million.
Vornado Realty Trust said on its call that funds from operations reached $126.6 million last quarter (considerably outpacing last year’s third-quarter number of $114.5 million) with revenue also up from last year ($467.6 million versus $453.7 million).
Come January we’re expecting even more fireworks as far as those big office owners are concerned. After a somewhat lackluster September, Manhattan leasing came roaring back in October, rising some 54 percent, according to a report from Colliers. And November has been off to a pretty stellar start with MetLife growing its footprint from 450,000 to 500,000 square feet at 200 Park Avenue, which more frequently goes by the name the MetLife Building. (Those old-timers among us will remember it as the Pan Am Building. Pan Am was an airline, kids.)
Oh, and a nice big chunk of Class A space is probably about to hit the market.
We can report a number of movements within the industry last week.
At CO’s Office Forum at Rudin’s 3 Times Square on Wednesday, the U.S. General Services Administration’s Ed Forst announced from the stage that he had named Cushman & Wakefield’s Mark Weiss as commissioner of the GSA’s Public Buildings Service and the 360 million square feet of property it operates.
Speaking of Cushman, we also learned that Gene Spiegelman is rejoining the firm after a stint as vice chairman at Ripco Real Estate.
Over at TF Cornerstone, Michael Gordon was hired away from the Walt Disney Company to lead construction of 175 Park Avenue, the 95-story, nearly 3 million-square-foot mixed-use development TFC is planning with RXR that should begin construction next year. (Now, Disney’s the kind of razzle dazzle any builder needs!)
And Adam Griff, a strategy director at architecture and design firm Gensler, has gone over to JLL to become managing director in the nonprofit, education and government department.
Sunday reading
Phew! It’s been a long week. (CO’s office forum was not our only conference last week — CO Finance had one, too!) But this is the time to sit back and read up on CO’s Lenders Issue, which published last week.
This was our interviews with 20 of the top lenders in the business about things like higher-forever interest rates, whether the window for opportunistic investment is still open, and if it’s better to be a borrower or a lender right now. (Neither, according to Polonius.)
While you’re at it, why not read our little history of Brooklyn’s Hotel Bossert which is about to undergo some very big changes.
See you next week!