With Data Centers, Lenders Are Getting a Lot More Selective
Lingering skepticism about the properties as a distinct asset class, coupled with tense opposition to new development, leave challenges and opportunities for financing
By Andrew Coen October 27, 2026 12:00 pm
reprints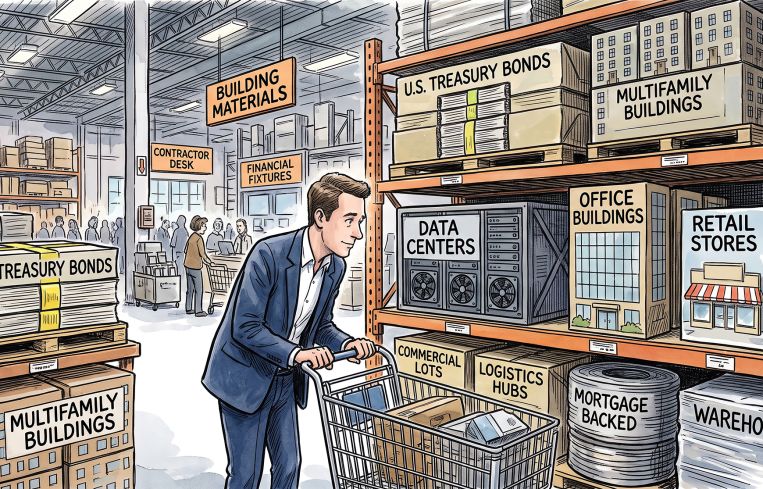
The rising profile of data centers in commercial real estate investment — and in the body politic — is making lenders more guarded about where, and to whom, they loan money. The greater scrutiny could actually turn out well for some owners and operators, while others find it tougher to obtain financing or refinancing.
Bank lenders committed an estimated $121.91 billion in credit for data center properties in 2025 with an average loan amount of $1.2 billion, according to data from S&P Global Ratings.
Commercial mortgage-backed securities (CMBS) issuance for data centers reached $11 billion in 2025, up 266 percent from 2024, according to a January 2026 report from the CRE Finance Council. CMBS issuance for data centers reached $4.9 billion in the first half of 2026 encompassing 9 percent of the total single-asset, single-borrower market, according to an August 2026 report from CBRE Capital Markets projecting continued lending momentum as development projects reach stabilization and seek long-term financing.
Despite macro volatility that has hit the CRE debt markets from rising interest rates and higher inflation from the war in Iran, data center lending continues to advance in 2026, with deals actually getting larger, according to Chris Lozinak, managing director with Newmark’s global debt and structured finance group. Lozinak noted, though, that lenders are becoming more selective with deals as groups explore exposure limits to the sector, specific sponsors or tenants.
“Lenders are becoming more picky with sponsors because as much as people like to think a data center is effectively an industrial building with an abundance of power, building a data center is is not like an easy task, and it takes groups that have deep, deep expertise in the space to be able to execute on these, deliver on time and on budget,” Lozinak said. “They want to know that the group that they’re lending to has a proven track record, and that the sponsor has the right people internally, and that they really have a pathway to continue to grow with them.”
The data center sector is confronting new unknowns in 2026, with increased political pushback highlighted by New York Gov. Kathy Hochul’s July executive order that enacted the nation’s first statewide moratorium on construction of large data centers. It also directed state regulators to create new standards for addressing environmental, energy and water-use impacts.
The lending climate for data center construction loans has also shifted in the last couple of years, according to Lozinak, from bank balance sheet loans to more private credit shops as banks scrutinize the sector more. Lozinak said many large private equity or private credit funds have dry powder to deploy and are positioned to take advantage when some banks scale back some of their data center construction lending exposure.
As banks grow more cautious with data center lending, opportunities are arising for private lenders to fill the void.
Blue Owl Capital, which has expanded into data center lending to complement its vast equity investments in the sector, is poised to benefit from the banks’ increasing selectivity. The firm provided a $975 million loan in June 2026 to a joint venture between Corscale Data Centers and Affinius Capital for the recapitalization of a newly completed, fully leased facility at the Gainesville Crossing Data Center Campus in Northern Virginia as part of its credit push into digital infrastructure assets.
“Bank selectivity is a technical imbalance, not a fundamental one,” said Marc Zahr, co-president at Blue Owl Capital. “A tremendous amount of financing came to market in a short period, and when supply increases that fast, pricing adjusts until more capital comes in. The market is also drawing a clear line between projects with long-term leases signed upfront and speculative projects without them.”
The construction lending data center market is nearly entirely predicated on pre-leasing from established tenants like Amazon, Google, Microsoft or Meta, according to Lozinak. There are very few speculative builds despite a nationwide vacancy of around 1 percent.
Lozinak noted that the stabilized data sector lending market is less established than the construction side, with CMBS and asset-backed securities financing much of the refinances. He said the next 12 months could see an uptick in refis with borrowers who have investment-grade tenants better equipped to obtain fresh capital.
The higher cost of capital in late 2026 with the 10-Year U.S. Treasury yields crossing the 5 percent threshold for the first time since 2007 has also meant more selectivity from bond buyers for data center debt.
“With the macro volatility and the movement in Treasurys, bond buyers are going to start reassessing how they play in these various different markets,” Lozinak said. “They’re going to be looking at the relative value in today’s market versus what else they can park their capital in, so I think you’re certainly going to start to see bond buyers become increasingly more just like the lenders in becoming more picky and selective over what they’re doing.”
The CBRE report showed that data sector vacancy in North America fell to around 1.4 percent in the first half of 2026 from the year-ago period despite record supply. Net absorption across primary markets increased by 11.7 percent year-over-year to 1,456.2 megawatts in the 2026 first half, with total construction capacity jumping 24.8 percent to a record high of 7,481.1 megawatts, according to CBRE. There were also $1.7 billion of investment sales in the first six months of the year, CBRE data shows.
The largest and most active data center developers are continuing to succeed in securing ongoing financing from lenders on multiple projects, according to the CBRE report. This trend was underscored when Related Digital and Blackstone landed $16 billion in construction financing led by PIMCO-managed funds for an Oracle-leased data center campus in Saline Township, Mich., in April.
Liquidity from bond investors for data center issuances remains strong in late 2026, aided by low vacancy rates and healthy leasing demand with tenants often signing long-term leases, according to Tom Rugg, co-head of U.S. large loans in debt and structured finance at CBRE. Rugg stressed, though, that investors lately have sought slightly more spread and coupon to offset increased supply in the market and negative AI headlines.
Both lenders and investors have been increasingly selective in the data center sector based on location and tenants. Rugg said that reflects how the CMBS, single-asset, single borrower market has responded to evolving credit dynamics in the asset class.
“The market is showing a bit of differentiation in credit quality in terms of the ultimate spread in the pricing of the deals,” Rugg said. “The market has also shown an ability to differentiate the underlying credit of the tenant and being able to ascribe a tighter print to an underlying lease backed by a company that has a very strong credit rating from those that may not be viewed as quite as strong as that very top tier.”
Despite some of the tailwinds backing data centers of late, traditional mortgage lenders have been more reluctant to lend on them since the assets often fall under project and infrastructure finance strategies rather than traditional real estate, according to Nicole Fenton, a partner at law firm HSF Kramer.
“I think that the problem with data centers is I don’t know if it’s truly real estate, and, the more I work on data center transactions, I don’t see them as real estate transactions, and they are more complicated,” Fenton said. “Once the building’s built, it’s really an operating facility. So, with that, it has a lot of high-tech equipment that is expensive, so it’s really a business operation more than anything.”
Fenton noted that data center deals often stretch far beyond the real estate boundaries such as financing equipment for these projects or on-site power plants. She noted that some lender clients, rather than deploying capital strictly for data centers, are exploring the possibility of commoditizing loans for a portfolio of power-owned land sites that could be utilized for data centers or other industrial uses.
No other states have followed New York in enacting a data center moratorium, but 13 states have explored “substantially unwinding” tax incentives for these projects, according to data tracked by the National Conference of State Legislatures. The increased opposition to data centers is also highlighted in a May 2026 Gallup poll showing seven in 10 Americans oppose these developments in their community.
The New York moratorium and community opposition to data centers forged across the country in many rural states have created another layer of risk for debt investors.
“With a data center, in some respects you’re underwriting a lot of your risk upfront because you need to have your end user in place, and you need to make sure that they’ve cleared the playing field for entitlements or the pathway to get to entitlements and to get to community buy-in,” Fenton said. “You may see lenders who are willing to finance the actual construction of the building, but I don’t think that that’s really where the biggest money is, as the big dollars are in the project finance and infrastructure element of it.”
Elevated resistance to data centers is still not expected to meaningfully slow any financing momentum for the sector.
Blue Owl’s Zahr said data center lending will continue to increase with banks, private credit firms, corporate bonds, CMBS deals and equity players all contributing since the capital required to build digital infrastructure to meet AI trends is too large for any single financing market. He noted that lenders are attracted to data centers as an asset class due to the very low vacancy rates, with leases running 15 to 20 years mostly to investment-grade tenants.
“The question for lenders is no longer whether to finance the build-out,” Zahr said. “It is which assets, structures and tenants to finance.”
Andrew Coen can be reached at acoen@commercialobserver.com.