Sunday Summary: Don’t Fear the Data Center Reaper
By The Editors November 22, 2026 9:00 am
reprints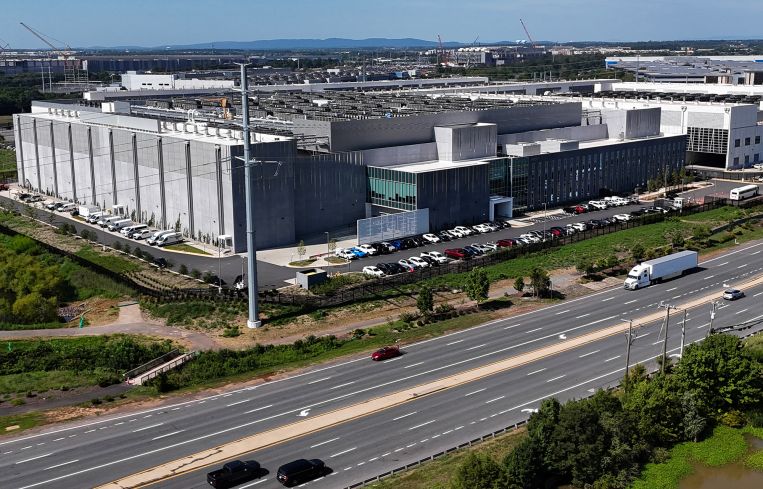
For those of our readers who own stocks of any kind, we just hope you didn’t look at your 401(k) or your portfolio in the last few days.
Indeed, looking at ours, the only description that came to mind was Jay Sherman’s memorable phrase.
Be it the stories of Chinese espionage; or political backlash to data centers; or big, public AI fails (real or perceived); or runaway capital expenditures and borrowing from the AI companies, the country is taking a second, hard look at artificial intelligence — and the accompanying data centers — and it has resulted in a big tech selloff.
To be very clear: The backlash is real. Loudoun County — the Northern Virginia home to more data centers than anywhere else on the planet — announced a yearlong pause on data center development last week.
And this is no mere virtue signaling: There are 33 active applications for data centers and substations currently awaiting approval from the county. (Although some of the Loudoun County centers in question will be grandfathered into development.)
All that being said, a number of major real estate investors in data centers aren’t shying away from the asset. In fact, some might be taking advantage of the fact that these centers might be harder to build in the future.
For instance, Blue Owl Digital Infrastructure Trust — an affiliate of Blue Owl Capital, the big daddy of data center investment and development — plunked down $779.5 million for a 54-megawatt data center just 20 miles outside of Loudoun County.
Moreover, Blue Owl doesn’t seem worried about financing the purchase; they’re getting $513 million in capital in the CMBS market for the deal.
Also, Commercial Observer learned that Blackstone Digital Infrastructure Trust (BXDC) — the data center arm of Blackstone — entered into a $5 billion agreement with Amazon Web Services for a 75 percent interest in two data center campuses in Mississippi and the Chicago area.
And, while companies like Blue Owl and Blackstone can afford to sit back and wait out the public discord, investors are still handing out money to much smaller AI companies with good potential. (CO panelists remained relatively upbeat on the topic in our AI & Innovation Forum on Nov. 18.)
Just last week, Bevado, an AI platform that automates communication between home buyers and sellers, announced that they had raised $10 million in seed funding. And AI-first companies, like the architecture firm Cove, have the capital to bulk themselves up with purchases like that of the Deerfield Beach, Fla.-based architecture firm GHA.
All of which is to say, it’s far too early to assume that AI and data centers will go the way of the life sciences asset class (which might be showing signs of life … even if the signs are still fairly dim).
Talking turkey
Next week is Thanksgiving, and as we contemplate all the sumptuous delights that await us — and eventually sigh, “Screw it, there’s always GLP-1s” — we noticed a number of comestible retailers that have signed leases that will push weight loss drugs from the theoretical into the essential.
First, Three Cherries Hospitality announced plans to open a new tavern (fittingly enough called Three Cherries) at 15 First Avenue, where the cocktail menu will pay homage to the 1970s and `80s. Gnarly!
Second, Shin Jidai — another tavern, but of the Japanese variety — also selected a spot in the East Village at 26 St. Marks Place for its first U.S. location.
Third, Archives of Us — a matcha chain that comes out of L.A. — signed a 2,400 square-foot-lease for its first New York location in (you guessed it) the East Village at 84 Second Avenue.
Of course, not all of the F&B activity is happening in the East Village. A few avenues over, Danny Meyer’s Union Square Hospitality Group signed an 8,000-square-foot lease at 21 West Eighth Street in the old Loring Place spot. (Check out Meyer’s new book if you’re looking for some hospitality-related reading over the holidays.) And, over in NoHo, the famed London jazz club Ronnie Scott’s took an 11,739-square-foot lease at 250 Mercer Street.
Moreover, it’s not just food and beverage that’s making moves. Curbline Properties announced that it had laid out an astonishing $888.9 million for 82 convenience shopping centers around the corner — with more on the way.
And the Real Estate Board of New York issued a retail report naming Williamsburg as the shopping capital of Brooklyn, with asking rents along Bedford Avenue reaching $450 per square foot.
Just remember that on Black Friday!
Sunday reads
Despite the overblown hopes of some that Kevin Warsh’s ascent to the top job at the Federal Reserve would usher in a new era of permanently lower interest rates, reality has largely set in.
“Deals haven’t disappeared, they’re just taking longer,” said Joseph Fingerman of Peapack Private Bank & Trust. “As rates change during the due diligence process, both lenders and borrowers may need to revisit their assumptions.”
“Taking longer” means more work going into deals. And that means a lot of bankers are hustling.
Last week we wrote about two such bankers: Wells Fargo’s Steven Caldwell, who heads the bank’s CMBS practice, and Scott Shepherd, who was brought in to straighten out Flagstar Bank’s massive book of delinquent loans in the wake of 2023’s regional banking crisis. Both have stories that you should take your time reading.
And, if you are eager for more, remember how Fannie Mae and Freddie Mac were going private earlier this year?
Yeah, that’s probably not going to happen.
Happy Thanksgiving!