COPA Passed. Don’t Expect It to Reshape New York City Multifamily.
The revived bill is far narrower than the one that stalled for six years, and the buildings it targets were already struggling to find buyers
By Lev Mavashev October 28, 2026 8:40 am
reprints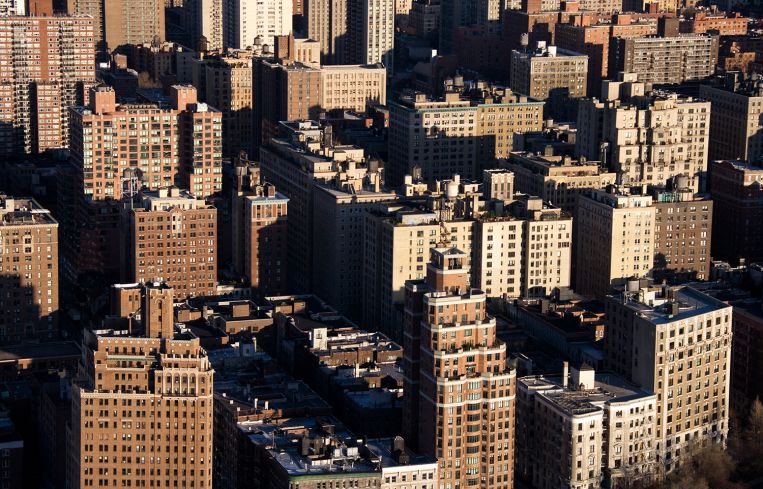
After six years of stalled drafts, revisions and lobbying, the New York City Council finally passed the Community Opportunity to Purchase Act. The headlines came fast, and so did the reactions. One camp calls it a historic win for tenants. The other calls it the end of the free market for New York City apartment buildings.
Both are overstating it.
Not last year’s COPA
Look at what actually passed. Earlier versions of COPA would have given qualified nonprofits a right of first refusal on a broad swath of the city’s multifamily stock. The market pushed back hard, and for good reason.
The revived bill is a different animal. It targets a narrower group of distressed and at-risk buildings, not the entire multifamily market. Nonprofits and certain city-designated joint ventures generally get 20 days to express interest, 70 days to make an offer, and a possible 15-day window to match a third-party bid.
That distinction matters. The well-maintained walk-up in Park Slope, the mixed-use building in the East Village and the free-market elevator building in Downtown Brooklyn are not the focus of this law. Anyone telling you COPA now applies to every building sale in New York City hasn’t read it.
So which buildings does it actually touch?
Buildings nobody was bidding on
Here is the part that gets lost in the political noise. The buildings in COPA’s crosshairs have not had a deep buyer pool for years.
Distressed, heavily rent-stabilized buildings with serious violations, deferred maintenance and expenses that have outrun legal rents have been the hardest product in the city to trade since 2019. The third quarter made that plain. In the Bronx, a six-building, 306-unit rent-stabilized portfolio around Creston Avenue sold for $15 million, roughly $55 per square foot. With the rent freeze now applying to stabilized leases and the 10-Year Treasury above 5 percent, buyers for this product are few and extremely price-sensitive.
For many of those owners, COPA may turn out to be less of a threat and more of a lifeline.
Plenty of them have been hoping for exactly this outcome: a structured way to sell to their tenants, the city or a mission-driven nonprofit with access to subsidies that private buyers don’t have. If the program is funded and run properly, it could create an exit where there wasn’t one.
Meanwhile, the rest of the market keeps trading. New York City recorded 256 multifamily transactions totaling $1.56 billion in the third quarter, according to Alpha Realty’s third-quarter market report, with deal count up 3.2 percent year-over-year. Buildings under 10 units drove the quarter with 148 deals, up 20.3 percent from a year earlier. Manhattan alone generated $928.3 million, about 60 percent of citywide volume.
That activity rests on assets COPA largely doesn’t reach.
Uncertainty is still a pricing input
That doesn’t mean the bill has no consequences. Where it applies, it changes the math.
When buyers underwrite a building, they aren’t looking only at income and expenses. They’re also judging how certain the transaction is and how quickly they can close. Add up to 105 days of potential process and a matching right, and you’ve added execution risk. Private buyers will price that in, with lower bids or by passing altogether. Lenders will do the same.
Then there’s the question nobody can answer yet: Do the qualified buyers actually have the money?
Distressed buildings need capital, not just new owners. Many need substantial investment in repairs, systems and modernization. A change of ownership without the capital and operating experience to back it doesn’t fix a building. It moves the problem from one balance sheet to another.
Preserving affordable housing and improving conditions for tenants are important goals. But that happens only if the buyer can fund the capital plan on day one and run the building on day 1,000.
What matters now
For most owners, COPA shouldn’t change the plan. If your asset isn’t in a distressed category, the bigger drivers of your value remain interest rates, rent regulation and the depth of the buyer pool.
If your building could fall under the program, now is the time to understand the timelines, organize your documentation, and decide whether a qualified entity is a risk to manage or a buyer to cultivate. For some owners it will be the second.
For the city, the test is implementation. Clear eligibility rules, firm deadlines, real funding and qualified buyers with operating track records will decide whether COPA preserves housing or just adds friction to transactions that were already hard to finance.
New York has no shortage of investors willing to put capital into multifamily housing. But capital needs predictability.
The real test for COPA is whether it can meet its housing-preservation goals without making already difficult transactions harder to finance and close.
Lev Mavashev is the founder and principal of Alpha Realty, a New York brokerage focusing on multifamily.