SASBs Dominate Conduits 3 to 1 in 2026 CMBS Market
By Liam Mulcahy October 26, 2026 8:55 am
reprints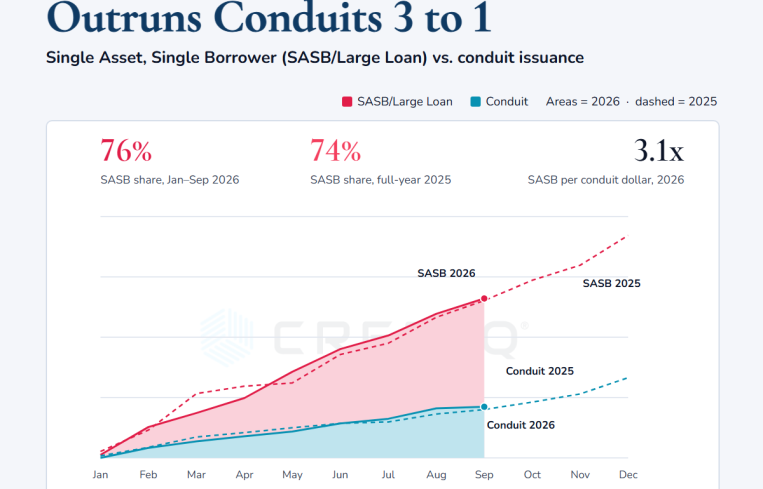
Single-asset, single-borrower (SASB) deals account for 76 percent of 2026 private-label commercial mortgage-backed securities (CMBS) issuance through September. Inside this volume, money is rotating from office and retail to apartments and hotels, and seven banks originate most of it.
In February, one loan on the Cosmopolitan of Las Vegas became a $3.05 billion bond deal on its own. No conduit priced this year came close as the biggest, BMARK 2026-V21, pooled 49 loans into $1.2 billion. Fifteen single-borrower and large-loan deals were bigger than that.
Through September, SASB and large-loan deals totaled $66 billion, against $21.2 billion of conduits: $3.12 for every conduit dollar, and 76 percent of private-label CMBS issuance. Combined volume of $87.2 billion is up 2 percent from the same months of 2025, with SASB up 1 percent and conduits up 6 percent. SASB out-issued conduits in every month of the year.
It wasn’t always this way.
In the first nine months of 2017, 2019, 2020 and 2023, conduits out-issued single-borrower deals, and SASBs’ share was 42 percent in 2017. Conduit volume has stayed in a narrow band, $13 billion to $28 billion in each January-to-September stretch, while SASB issuance has more than doubled.
SASB has surged in strong CMBS years (2021, and 2024 onward) and retreated in weak ones: Its share fell to 37 percent in 2020 and to 47 percent in 2023.
The biggest SASB deals read like a list of the country’s marquee assets. After the Cosmopolitan, there is a $2.1 billion Jersey City, N.J., multifamily portfolio, a $2.05 billion QTS data center portfolio financed by nine banks, and $1.9 billion on Two Manhattan West. Manhattan office and mixed-use towers, including 9 West 57th Street, One Madison Avenue and 10 Hudson Yards, fill out the top 10.
Where the money went
The two channels finance different buildings. Conduits remain the home of everyday collateral, with multifamily 26 percent of the balance and retail 13 percent spread across 1,067 loans averaging $20 million. SASB money goes to trophy assets and big portfolios.
Office is still the largest SASB property type at 19 percent of balance, but SASB office volume fell to $12.5 billion from $22.4 billion a year earlier, and SASB retail halved to $5.1 billion.
Apartments and hotels took up the slack with SASB multifamily rising to $10 billion (up from $2.9 billion) and hotels to $11.3 billion (up from $8.8 billion). Data centers also reached $6.2 billion, encompassing 9 percent of the SASB balance. Across both channels, multifamily’s share more than doubled to 18 percent (up from 8 percent), while retail fell to 9 percent (down from 16 percent).
Structure differs, too, with 60 percent of SASB balance
floating-rate, while conduit loans are fixed, 90 percent of them interest-only, at a weighted average coupon of 6.43 percent.
The originator leaderboard
Seven banks write most of the CMBS market.
Goldman Sachs, Wells Fargo and Citi lead CRED iQ’s 2026 ranking of loans contributed to conduit and SASB deals, and the top seven account for 80 percent of the attributed volume. Goldman Sachs originated $12 billion, with $10.1 billion of it in SASB deals. Citi led conduit lending with $2.6 billion.
The ranking has barely moved from 2025 with the same eight banks making up the top eight, with Citi climbing to third and Morgan Stanley slipping to fifth.
Issuance is running slightly ahead of last year, and SASB still sets the pace with three of every four private-label dollars. What has changed is the collateral: less office and retail, more apartments, hotels and data centers. Conduits keep financing the broad middle of the market, one $20 million loan at a time, but the big money in 2026 is moving one asset at a time.
Liam Mulcahy is senior product manager for CRE data and applied AI at CRED iQ.