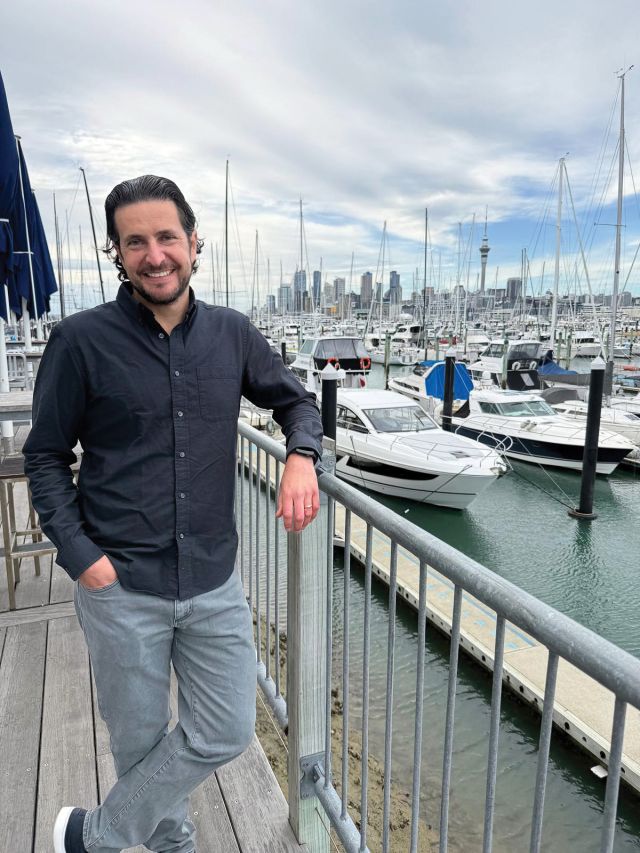
Jason Kollander
Head of real estate credit at BDT & MSD Partners
Has the can been kicked fully down the road when it comes to loan extensions, or is there more leg action to come?
There’s more to come in terms of amendments and extensions given what was the expectation of rate cuts in 2026. While many issues have been worked out through increased refinancing and acquisition activity, challenges remain concentrated in legacy vintages and weaker assets, driven by sector and submarket.
There have been real winners, however, so it’s not an accurate depiction to paint the entire market with the same brush. Commercial real estate values have already undergone a meaningful reset post-2022, and lending activity has recovered across many sectors. The remaining pressure is largely in loans originated prior to that repricing, where cash flows haven’t recovered and values haven’t supported an accretive refinancing. For those assets, another extension may no longer be the answer.
We’re likely to see more equity infusions, partial paydowns, cash-in refinancings, and sales as owners and lenders work towards resolutions.
How are projections for higher-for-longer interest rates impacting your lending strategy today?
We’re underwriting with the assumption that rates remain elevated, rather than relying on rate cuts to make an investment work. That means building in a margin of safety for exit value, incorporating an appropriate structure in the loan documentation, and performing equity-like diligence on the underlying assets, markets and sponsors.
We are focused on debt service ratio cushions, protecting against rate volatility through hedges, and being realistic about residual exit values to drive refinancing. We’re also focused on sectors where underlying fundamentals support returns, including industrial, higher-end residential and hospitality.
The principle is straightforward: An investment should work at today’s rates. If rates decline, that’s extra protection — not something we need to achieve our return and get repaid.
What’s your competitive edge in deals today, and who are you competing against most often (banks or non-banks)?
We compete primarily with other non-bank lenders, but winning deals isn’t always about offering the lowest rate. Reliability, relationships and the ability to execute efficiently matter just as much. Our roots in the Dell family office continue to shape how we approach lending.
We think like owners, take a long-term view of our relationships and actively manage our investments rather than simply servicing loans. Sponsors want to know that their lender understands the business plan, will deliver on its commitments and can be a constructive partner when circumstances change.
Do you expect more or fewer loan sales in the year ahead?
More.
Buyers and sellers are getting closer on valuations following the market’s repricing, and there’s more capital available to finance transactions like that. At the same time, some earlier vintage loans are reaching the point where another extension isn’t the best solution or even on the table. We would expect that to bring additional opportunities to market.
We’ve historically been willing to invest during periods of dislocation, particularly when we have conviction in the sponsor and underlying real estate, but another lender needs to reduce its exposure. We expect to remain selective as those opportunities emerge both on single asset and portfolio loan sales.
Is AI indeed going to kill us all?
We’ll leave the existential risk question to the philosophers, Morpheus and John Connor.
From a real estate perspective, AI may end up being a net tailwind for the sector. In certain markets, we are seeing growth in AI-related jobs and demand for office space and residential units in markets where these companies are concentrated.
The more immediate impact is on infrastructure. The enormous investment in AI is driving some of the strongest data center and related industrial demand we’ve seen in a generation, with benefits extending to nearby office, multifamily and hospitality markets. We also practice what we preach — we have leaned into AI tools across underwriting and portfolio monitoring.
So, we are not just lending against the trend, we are living it.
If you were marooned on a desert island, which three items would you bring, and what would be your key survival skill?
Three items: a Dell laptop and charger with hot spot, a satellite phone, and unlimited Tony Dragon’s (IYKYK).
Key survival skill would be patience. Underwriting and investing throughout cycles teaches you to sit with uncertainty without panicking, and to play tactical offense — this turns out to be surprisingly good training for being stranded on an island.
Though, between the laptop and satellite phone, let’s be honest, I would probably just be on calls to see who owns the island and if we could finance it.
Lightning Round:
Super Bowl or World Cup? Super Bowl.
Orcas or yachts? Save the whales.
If you could train AI to do one new thing, what would it be? Continue to better serve clients.
Best vacation you ever took? Any of the hotels in our portfolio.
Last time you said, “Phew, that was a close one!”? A recent realization.
Conversions: “Keep `em comin’ ” or “Sooo 2020”? Bring `em on!
Sun Belt multifamily or Boston life sciences? Sun Belt multi (as a lender!).
Book reader or phone scroller/email checker before bed? All of the above.
Describe your portfolio in one word? Tactical.
Fitness activity of choice? Golf (I get it, it’s not exercise).
The Stories Behind the List