After Tuesday, the Data Center Industry Is Facing an Allocation Crisis
By Suhail Tayyeb November 6, 2026 11:41 am
reprints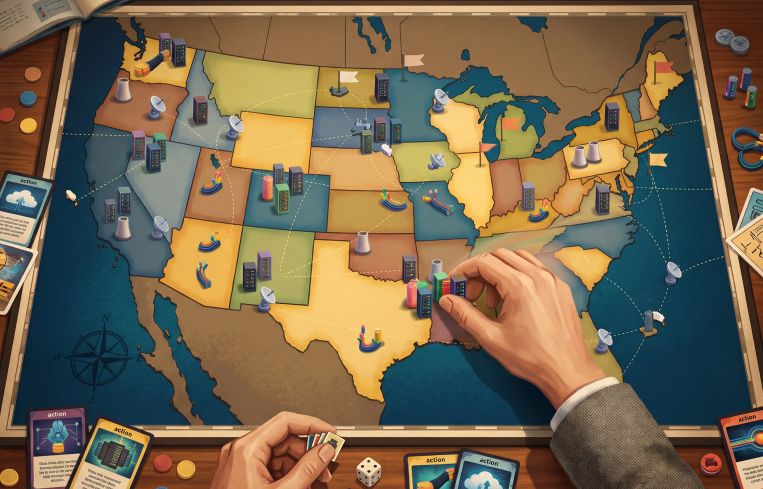
Texas, home to roughly a quarter of planned U.S. data center capacity, just elected a governor who promised to pause data center approvals. The vote was not about whether America needs more compute. It was about who gets the power, water and land to build it.
The data center industry does not have a demand problem. Demand for compute is growing, capital is available, and developers are searching for sites across the country. The harder question is who gets the resources required to satisfy that demand: power, water, land, transmission, transformers, skilled labor and capital. None is unlimited, and the same projects increasingly compete for all of them.
For much of the current boom, the central question has been how much demand artificial intelligence will create. Once demand exceeds the infrastructure available to serve it, forecasting demand becomes less valuable than understanding allocation.
Power provides the clearest example. A utility can have dozens of projects requesting service and still be unable to build generation, transmission and substations fast enough to serve them. A developer may control land and have an interested customer, but neither guarantees power when the project needs it. The question moves from how much electricity data centers require to which projects receive it first.
Water follows the same pattern. A region can have enough water overall and still face hard choices about where it goes. A large campus competes with agriculture, manufacturing and housing for the same watershed. Transformers have manufacturing lead times. Skilled workers cannot be everywhere at once. Even capital now separates projects that merely control land from those that can secure the infrastructure to operate.
AI is currently competing with factories, housing and electrification for the same systems. Communities want economic development without absorbing disproportionate infrastructure costs.
On Nov. 3, that competition became political.
In Texas, Gina Hinojosa defeated Gov. Greg Abbott after campaigning on a moratorium on data center approvals until the legislature passes new rules. Ohio elected Amy Acton, who supports a moratorium. Georgia elected Keisha Lance Bottoms, who made developer accountability central to her campaign. Voters in at least 10 states backed restrictions or rejected projects outright.
This is not a partisan story. Abbott, a Republican, had already paused data center interconnections pending an audit of hundreds of projects in the grid queue, and halted environmental permits for data center projects statewide. In Ohio, every candidate for governor called for restrictions. Hinojosa has signaled she would go further and extend the pause to all data center approvals.
Allocation is no longer only a utility decision. Governors, legislatures, public utility commissions and county boards now decide, and the community is in the room. Demand did not go away. The number of gatekeepers grew.
I learned this years ago entitling residential land in Castro Valley, Calif. I controlled the site, but it took multiple rounds with the neighbors before I could get approvals to build homes. Data center developers are now learning the same lesson at gigawatt scale.
When demand is uncertain, the advantage belongs to those who identify where it will emerge. When demand is obvious but resources are scarce, the advantage shifts to those who control, secure or influence allocation.
That changes the map. Former industrial markets, including many around the Great Lakes, hold transmission systems, substations and water infrastructure built for economic activity that has since disappeared. Other markets offer inexpensive land but cannot deliver infrastructure on time. And, as Ohio just showed, resource-rich markets face the same political questions. The most attractive market is not the one with the most resources. It is the one where those resources can be allocated on an acceptable timeline.
Theoretical capacity and allocable capacity are different things. A megawatt promised after the customer’s deployment window has little value. Water that cannot be permitted for a particular use is not available water. Transmission that depends on upgrades years away is not infrastructure that can serve a project today. The real question is what can be allocated, to whom and when.
Investors should look beyond demand forecasts. Diligence now needs to answer six questions, in this order:
- Who pays? Does the project have a credible answer when the community asks?
- Who controls the power, and who has priority in the interconnection process?
- Which infrastructure upgrades are funded, and when will they be delivered?
- Where do the water rights sit?
- Can the equipment, especially transformers, be procured on schedule?
- Does the workforce exist to deliver the project?
The industry spent the last several years trying to understand how large AI demand could become. The next phase will be about which projects, companies and communities actually get the resources to serve it.
The constraint is no longer demand.
It is allocation.
Suhail Tayyeb is clinical assistant professor at New York University’s Schack Institute of Real Estate and director of the Center for the Sustainable Built Environment.