Presented By: Flatiron Realty Capital
Luxury Bridge Lenders Are Having a Moment. Flatiron Realty Capital Tells Us Why.
How an all-cash luxury market broke its link to mortgage rates
By Flatiron Realty Capital November 17, 2026 12:00 am
reprints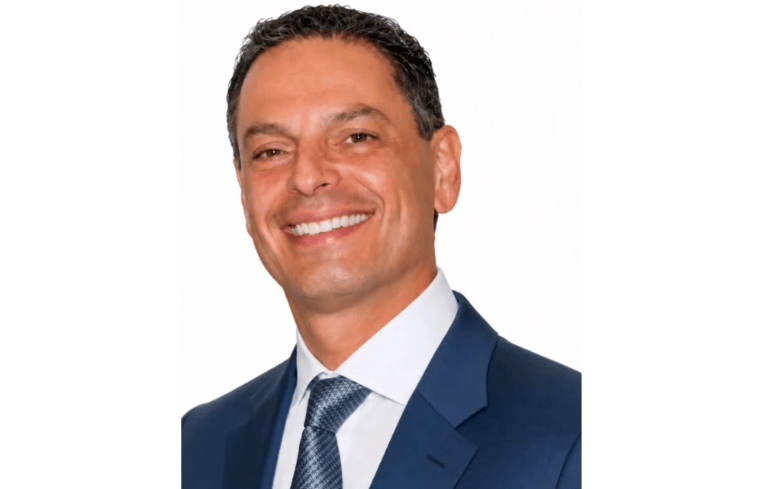
Michael and Ed Ostad bring a unique perspective to commercial real estate. As founding partners of both private lender Flatiron Realty Capital and the property management firm TriStar Management, the brothers have a deep involvement with, and understanding of, industry sectors from financing to property management and from luxury to affordable housing, along with everything in between.
Partner Insights spoke with Michael Ostad to get his take on the current state of affairs throughout commercial real estate.
Commercial Observer: What effect have higher interest rates and a massive rise in construction costs had on your lending business?
Michael Ostad: They’ve made our underwriting more conservative, and, at the same time, made our loans more valuable to the builders who get them.
We size loans to what a project can afford if it takes longer to sell, not in the best case scenario. In practice, that means a bigger interest reserve to cover carry through a longer sale period, built into the loan from day one. Higher construction costs mean we lend against cost, not projected value, and we keep leverage low. We need real contingency, not a line item nobody can draw on.
The flip side is that banks have pulled back from spec construction, especially at the high end. Good builders with good projects have fewer places to go, and certainty of close matters more to them than the last quarter point.
Have current market challenges made this a better or worse time to be a bridge lender?
In luxury, it’s a better time. In non-luxury single family, it’s a harder one. The difference is the buyer and the supply. In non-luxury single family, the end buyer needs a mortgage. At 7 percent, many can’t qualify. So builders sit on finished inventory and cut prices, or buy down rates to move it. A bridge lender’s exit depends on a buyer the rate market controls. In luxury, the high-end buyer often pays cash, and the rate barely touches the exit. So the lender’s risk is timing, not whether the house can sell.
We lend in supply constrained markets with huge barriers to entry like Palm Beach, Miami, the Hamptons and Aspen, Colorado. There is very little land, zoning and approvals are slow and strict, and nobody can flood the market with new product. Entry level markets can add supply quickly. These can’t.
What are the differences between how market challenges are affecting luxury builders and lenders and how they’re affecting builders and lenders of non-luxury single family projects?
Non-luxury builders face a buyer squeezed by rates and a market where supply keeps coming, especially in the sunbelt.
National inventory hit 1.6 million homes in September, the most since 2019, and about 43 percent of sellers were cutting prices. Luxury builders in Palm Beach, the Hamptons, and Aspen face the opposite for the reasons I just mentioned.
Higher costs can be priced into the finished house because the buyer is willing to pay for the quality.
For lenders, that changes the risk. In non-luxury, we worry about price cuts eating the equity. In luxury, the question is how long the right buyer takes to show up so we underwrite a longer marketing period, a missed season and a properly-sized interest reserve. Barriers to entry are key, and protect the builder and the lender alike.
How has the trend toward all-cash buyers in luxury markets changed the way Flatiron approaches lending for top-of-the-line luxury properties?
It makes the assets we lend against largely uncorrelated to mortgage rates. In most housing markets, the value of finished homes depends on what a buyer can borrow. When rates go to 7 percent, buyers shrink their budgets and prices follow.
At the top of the market, that link is mostly broken. In South Florida, according to MIAMI REALTORS®, 61 percent of million-dollar sales in the first half of 2026 were cash, as were 88 percent of sales over $10 million. The buyer’s ability to close doesn’t depend on the rate.
So when we underwrite a loan on these types of assets, we spend less time stress-testing rates, and more on the specific house. We look at the location, the street, and the comparable sales, not the market median. Combine that with supply-constrained markets, and you have collateral whose value holds up even when the rate environment turns against the rest of the housing market.
And of course, we partner with proven builders. The operator is always the first line of defense.
Along with your brother, Ed Ostad, you also own TriStar Management, which owns multifamily properties throughout New York. How are you finding multifamily ownership here given the current economic and political environments?
Ed and I have been at it for over two decades. The operating environment today is the hardest we’ve seen, but we think it’s made us better owners and better lenders.
Since the 2019 rent law changes, regulated buildings have had limited ability to recover the cost of capital improvements while taxes, insurance, labor and repairs keep rising. Higher rates have turned into refinancing problems across the sector, and many owners now face loans that were written for a different rate world.
So what it takes now is operating discipline, patience, and capital partners who understand the asset.
It’s a tough market, but it will work itself out.
Given your vast experience as both a multifamily property owner and a luxury property lender, how has your experience with each made you more effective at the other?
It’s about perspective. Seeing both sides has helped us understand the perspective of the borrowers that we lend to, and we know what investors, owners, and operators need from capital.
Also, being a lender taught us what an exit has to look like. We’ve been owners for decades, and still are, and we started lending in 2015. As borrowers, we know that certainty of execution is part of an investor’s underwriting. When you’re buying an asset, the price you can win it at depends on whether the seller believes you can close. A lender who is slow, retrades terms, or can’t fund on time costs you the deal or costs you money. That’s why certainty of close is central to how we lend. Our borrowers can underwrite our capital as a given, not a risk.
As owners, we learned that an asset is worth what the next buyer pays on the day you need them to pay it. That’s the lens through which we underwrite every loan that we originate. Owning also teaches you where budgets can break.
Has you seen any migration from New York to Florida due to tax fears over the past year or so? And if so, how has that affected your business?
Yes, it definitely shows up in the data and in who’s buying the houses we finance, and I think it’s for a variety of reasons in addition to taxes.
Out-of-state buyers were 10 percent of domestic buyers in South Florida in the first half of 2026. That’s up from 7 percent in 2024 and 2025. New Yorkers were the largest group by far at 34 percent of that group. Out-of-state driver’s licenses in South Florida rose 16 percent from a year earlier, with New Yorkers up 9 percent.
New York buyers also buy at the top. Their luxury threshold in South Florida was $5.9 million, against $2.4 million for Florida residents. For us, the Hamptons and Palm Beach are increasingly one buyer with two seasons. The family that summers in Southampton is closing on a house in South Florida.
The bottom line is, we think the best real estate investors, owners and operators return to the same capital source deal after deal. They come back to us because we’ve sat where they sit.