Weil’s Collapse Puts Law Firms’ $35.4B CMBS Footprint in Focus
By Liam Mulcahy November 9, 2026 10:33 am
reprints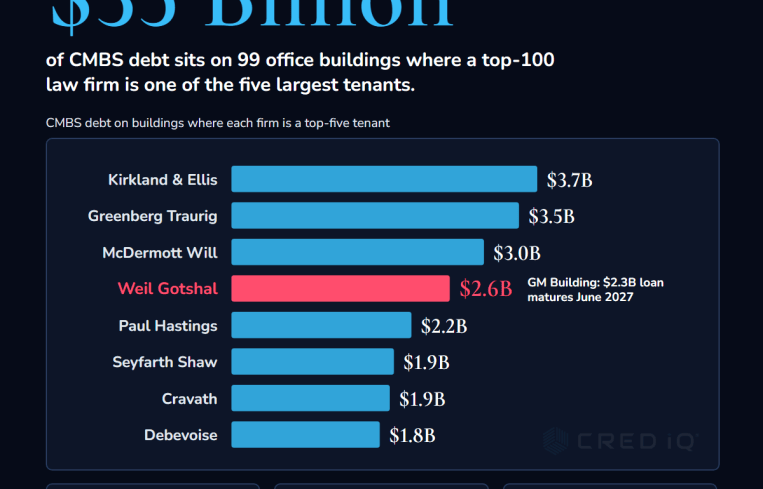
Law firm Weil, Gotshal & Manges has been in the General Motors Building on Fifth Avenue since the tower opened in 1968. It is still the largest tenant, with 447,075 square feet leased through August 2034, and, when the building’s $2.3 billion loan was securitized in 2017, the firm paid 19.4 percent of its gross rent.
The commercial mortgage-backed securities (CMBS) loan, split across BXP 2017-GM and 10 conduit deals, matures in June 2027. With Weil now winding down, the building’s lenders face a refinancing question they did not expect a year ago.
Weil is not an isolated exposure.
CRED iQ found Top 100 law firms among the five largest tenants in 99 office buildings backing $35.4 billion of CMBS debt across 192 deals. In 34 of those deals, carrying $15.9 billion, a law firm is the single largest tenant. The 69 firms occupy 16.5 million square feet in these buildings, and 55 percent of the debt is in New York.
Weil’s footprint shows how one firm can reach several deals. In Dallas, the law firm is a top tenant at the Crescent, refinanced in March through CRSNT 2026-MOON. It had signed an early renewal there at $54 per square foot, triple net, from August 2028 to 2039: a 67 percent increase over its in-place rent of $32.21.
The trophy towers are locked up
Big Law’s newest leases run longer than the loans. Cravath, Swaine & Moore’s 519,415 square feet at Two Manhattan West runs to 2044, nearly eight years past the maturity of its $1.9 billion loan. Debevoise & Plimpton has 530,722 square feet at the Spiral through 2042, McDermott Will is One Vanderbilt’s largest tenant through 2042, and Paul Weiss leases 765,956 square feet at 1345 Avenue of the Americas through 2047, 20 years after that loan matures.
The trophy towers are locked up
In 24 buildings carrying $5.8 billion, a Top 100 firm’s lease expires before the loan matures. Ropes & Gray’s 345,413 square feet at 1211 Avenue of the Americas expire in March 2027, 17 months before the building’s $1.04 billion loan comes due. At 425 Lexington Avenue, the lender has trapped cash since the loan closed this year because Simpson Thacher & Bartlett, with 642,838 square feet, plans to leave when its lease ends in 2033.
Fewer defaults, bigger holes
Law firm buildings default less often.
Nineteen of these defaults, with $3.2 billion of debt, are in special servicing equating to 9 percent of the balance, against 15.8 percent for CMBS office loans overall. But, when a firm leaves, the hole is large.
At the New York Times Building, Covington & Burling’s 197,450 square feet sit vacant. A $635 million loan defaulted at its December 2025 maturity, and Datadog has a right of first offer on the space.
In Los Angeles, Skadden’s 107,058-square-foot lease at One California Plaza was set to end in November 2024, the month a $287 million loan backing the property failed to pay off at maturity. A receiver now runs the tower, which is 55.1 percent occupied.
Keeping the firms does not guarantee a healthy loan. At 51 West 52nd Street, law firm Wachtell Lipton extended to 2034 and Orrick expanded and extended to 2038, yet the loan is with a special servicer at 0.64 times debt service coverage.
In San Francisco, Kirkland & Ellis is the largest tenant at 555 California Street through 2030, but the building is 74.3 percent occupied, coverage fell to 0.47 times in June, and the $1.2 billion loan matures in May 2027.
The takeaway
Law firms sign long leases and pay their rent, which is why these buildings default less often. The risk is concentration, as 27 of the buildings with $10.5 billion of debt have loans maturing by the end of 2027, the GM Building among them. Lenders will be asking whether the anchor firm is staying, moving to a new tower or, like Weil, going away.
Liam Mulcahy is senior product manager for CRE data and applied AI at CRED iQ.