Presented By: SitusAMC
How Investor Appetite is Driving Activity In the CMBS/CRE CLO Markets
As more and more first-time issuers enter the CRE CLO space and multifamily-focused conduit deals are on the upswing, commercial real estate securitization is proving to be an adaptable indicator of a healthy market.
Parker Umsted has over a decade of experience in the CMBS securitization industry, first with KPMG and PricewaterhouseCoopers, and today as managing director and head of securitization at SitusAMC, the leading provider of strategic outsourcing, advisory, talent, and technology solutions to the real estate finance industry.
Umsted spoke with Commercial Observer Partner Insights about the current evolution of the CMBS/conduit market.
Commercial Observer: Why have multifamily loans become such a larger part of the conduit/CMBS market over the past decade, and what has this increase meant for both issuers and borrowers?
Parker Umsted: For one, there’s been an increase in housing supply since COVID.
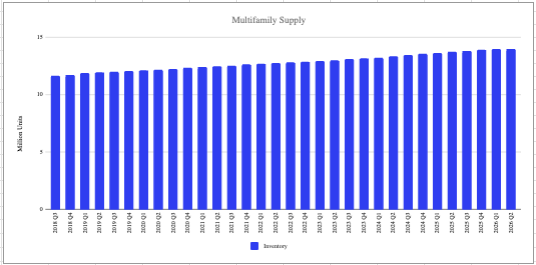
When interest rates were low, the housing market caught fire and everybody tried to get in. So that market increased significantly. Moving into a house then became less affordable as supply diminished.
Now, the industry is trying to build that supply back, and not only in traditional multifamily locations, in cities, but in commuter towns as well.
Due to all this activity, multifamily has continued to perform well, including from a default or debt coverage standpoint. I believe multifamily will continue to perform well, especially since the sector has proven to be more adaptable compared to other securitization asset types.
How has the structure of these loans changed as the market has grown?
There’s been increased scrutiny for sure. When you see a rush toward one property type, you tend to worry about the possibility of increased defaults. So we’re seeing things like covenant testing and occupancy requirements structured into loans.
Also, the multifamily space has always existed in the agency world with GSE’s. As multifamily has moved toward more of a traditional CMBS/conduit/CRE CLO space, you’ve seen more issuers underwrite these loans to meet industry standards, making those loans more flexible in terms of where their asset distribution can fall in the capital markets.
Is the increase we’re seeing in these loans the reason so many new CRE CLO issuers have entered the market?
Yes. During COVID, we saw a lot of conversions of office and hospitality to multifamily, so you started to see issuers move into the CLO space there.
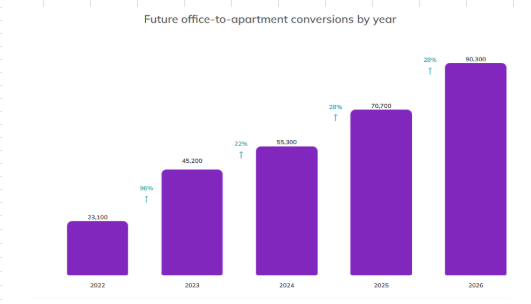
Also, we’re at a 70 or 75 percent concentration of multifamily in CRE CLO spaces this year. There were a lot of lenders focused on multifamily, and it became easy for them to say, “We have a warehouse line. We’ve already originated a strong pool of multifamily loans and this is an attractive execution where they can clear the lines.” This allows them to continue lending without having to originate these loans and take that risk with the loans sitting on their balance sheet.
What sort of companies are just now entering these markets?
The B securitization REITs did a lot in the multifamily-only conduit spaces, and we’re seeing agency-only lenders moving towards CLOs. We’re also seeing smaller non-bank lenders offering warehouse lines of credit. They’re working with big investment banks who not only have a warehouse line, but are also book runners and lead underwriters for CRE CLOs.
How has growing multifamily demand been affecting all this?
The good news is that the growing demand has helped to offset one of the biggest risks to the multifamily market, which is that after a significant increase in rent growth from 2021 or 2022 until early 2026, rent growth slowed as navigating the housing market became much more difficult for people.
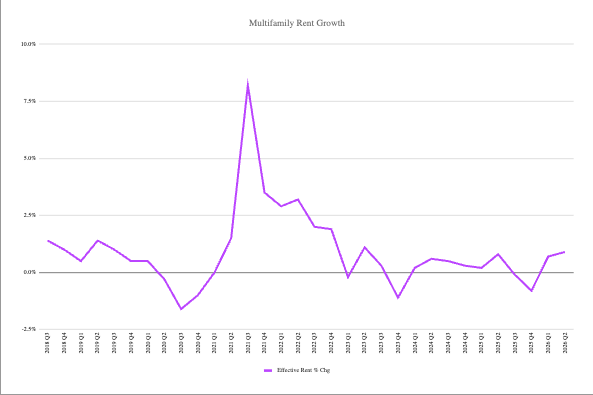
While the offset of where rent growth may have been is an issue for lenders, it’s now becoming a strength. Rents have stabilized, and we’re seeing tremendous demand for new multifamily properties.
Also, as the average age for first-time homebuyers continues to rise, the same is happening for the average age of renters, and that’s going to keep driving up demand.
What are some key factors first-time issuers need to take into account before entering the market?
One major issue for first-timers is the danger of thinking of this as a one-time exercise and just trying to get it off the books.
The CRE CLO space is all about managed deals, and it’s a continual process with extensions and modifications. You have to be in for the long haul with reliable, well-vetted partners that will help you develop a programmatic endeavor. The more successful the first FL1 is, the more successful you’ll be at convincing your credit committee that you need an FL2, FL3 and FL4.
Also, high credit quality and strong metrics that support a strong collateral pool are paramount. When you talk about CRE CLOs, you’re talking about non-stabilized properties. So the borrower’s business plan is a significant focus for rating agencies, investors and issuers. You need to know that it’s feasible and that the borrower has a solid track record.
Rates have fluctuated quite a bit over the past few years. How have those fluctuations affected the CMBS and CLO markets for multifamily?
CLOs use floating-rate bridge financing, and higher rates mean a more expensive cost of capital. One thing we saw when rates originally rose in 2022 was that it became very expensive to cap interest rates. So you have to think about that as a cost into this when you’re looking at trying to create an interest rate cap, and whether the cost could make this an unfeasible product.
When you work with borrowers that are familiar with the multifamily market, you can navigate some of the more perilous peaks and valleys. What’s really important is being thoughtful about your special servicing partners and making sure you have partners who can guide you through tough times, whether it’s for an extension or a modification. We saw a lot of issuers work with borrowers to get through those times in the hope that rates would start to stabilize.
The CMBS market is much more affected by uncertainty than by rising interest rates or geopolitical issues. We didn’t see a sharp increase in CMBS defaults in multifamily the way we did in retail or office. We did see increased scrutiny around underwriting standards. But the CMBS market was malleable in unexpected ways coming out of the great financial crisis as we saw the creation of multifamily-only conduits, and five-year deals that allow you to have short-term paper on the conduit market.
We also saw multifamily move significantly into the single asset space, which was dominated by hospitality and industrial for so many years. So while it has affected the pool concentration, if there’s investor demand, the CMBS and CLO markets have always found a way to get that product out there.